General educational information as of November 2026. It is not tax, legal, or investment advice and does not address your individual situation. It does not recommend any investment or product.
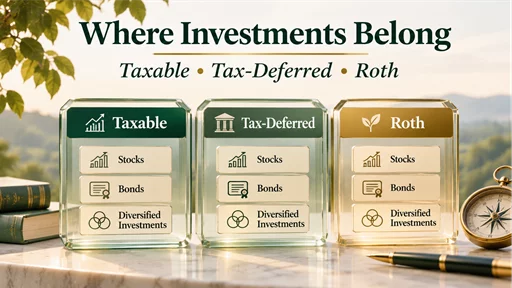
Most investors know that how much they hold in stocks and bonds, their asset allocation, matters. Fewer think about a second question: which account should hold each investment? Two investors can have the same overall mix and the same pre-tax return and still end up with different after-tax results, because accounts are taxed differently. Choosing which investments to hold in which accounts is called asset location.
This article explains the difference between allocation and location, how each type of account is taxed, the general principles people use, the practical limits, and where location does little. It does not recommend specific funds or products. All figures in the illustration are hypothetical.
Allocation versus location
Asset allocation is the overall mix of investments across stocks, bonds, and other asset classes. It reflects your goals, time horizon, and tolerance for risk, and it is the larger decision.
Asset location takes that mix as given and asks where each piece should be held to reduce taxes. As one source1 puts it, location "works alongside asset allocation, not instead of it." Another says allocation always comes before location.
Location does not change how much risk you take. It changes which account holds what, so the same portfolio, viewed across all your accounts, is the same.
How each account type is taxed
| Account type | Contributions | Growth | Withdrawals |
|---|---|---|---|
| Taxable (brokerage account) | After-tax | Interest, dividends, and realized gains are taxed in the year they occur, at rates that depend on the type of income | No additional tax on principal. Gains are taxed when you sell. |
| Tax-deferred (traditional IRA, 401(k)) | Often pre-tax | Not taxed while in the account | Taxed as ordinary income. Required minimum distributions generally begin at 73 or 75, depending on the individual's birth year under current law. |
| Roth (Roth IRA, Roth 401(k)) | After-tax | Not taxed | Qualified withdrawals are tax-free. The original owner of a Roth IRA has no lifetime RMDs. |
| HSA (a bonus category) | Pre-tax or deductible | Not taxed | Tax-free if used for qualified medical expenses |
In a taxable account, the type of income matters:
- Interest from most bonds and savings, and non-qualified dividends such as most REIT dividends, are generally taxed at ordinary rates, up to 37% for 2026.
- Qualified dividends1 and long-term capital gains (assets held more than a year) are taxed at 0%, 15%, or 20%. For 2026, one source3 lists the 15% rate beginning at $49,451 of taxable income for single filers and $98,901 for joint filers, and the 20% rate beginning at $545,501 for single and $613,701 for joint filers.
- Net investment income tax. An additional 3.8% may apply to investment income above $200,000 (single) or $250,000 (joint) of modified AGI.
- Municipal bond interest is generally exempt from federal income tax.
- Foreign tax credits are generally usable only for taxes paid in a taxable account.
- Step-up in basis. Assets held in a taxable account may receive a new basis at death, which can eliminate some or all previously unrealized gain.
The gap between ordinary rates (up to 37%) and long-term rates (up to 20%) is the main reason location matters.
General placement principles
These are common rules of thumb. They are simplified, and almost every one has exceptions.
Tax-deferred accounts tend to suit investments whose income is taxed at ordinary rates, because deferral shields that income each year. These typically include taxable bond funds, REITs, and high-turnover funds that distribute a lot of short-term gains.
Roth accounts tend to suit assets with the highest expected growth, because growth and qualified withdrawals are tax-free. Some sources3 treat an HSA the same way for placement. Where bonds belong when Roth space is available is debated, because the answer depends on assumptions about returns and time horizon, and analysts differ.
Taxable accounts tend to suit investments that are already tax-efficient: broad stock index funds, long-term stock holdings that distribute little, tax-managed funds, and municipal bonds. They also suit foreign stock funds, so that the foreign tax credit can be used. Gains can be deferred, and heirs may receive a step-up in basis.
Two further points from the sources2, 4:
- Holding municipal bonds in an IRA gives up their tax exemption, so they are usually held in taxable accounts if held at all.
- Whether U.S. or international stocks should go in the taxable account is described by one commentator as roughly "a wash."
An illustration with hypothetical figures
These figures are invented to show the mechanics. They are not a forecast.
Assume an investor has $100,000 split into a $50,000 taxable account and a $50,000 traditional IRA, with a target of 50% stocks and 50% bonds overall. Assume the bonds yield 4%, all taxed as ordinary income at an assumed 24% bracket, and the stocks pay a 2% qualified dividend, taxed at an assumed 15%. Ignore capital gains.
| Option A: bonds in taxable, stocks in IRA | Option B: bonds in IRA, stocks in taxable | |
|---|---|---|
| Annual tax on bond interest | $480 ($50,000 × 4% × 24%) | $0 (inside the IRA) |
| Annual tax on stock dividends | $0 (inside the IRA) | $150 ($50,000 × 2% × 15%) |
| Total annual tax | $480 | $150 |
Option B has about $330 less tax each year, or about 0.33% of the $100,000 portfolio, with the same overall mix.
This is a simplified comparison. It leaves out how the IRA is taxed when you withdraw from it, which can offset part of the advantage, and it ignores capital gains, changes in tax law, and your tax bracket in retirement. Published estimates of the benefit of location vary and are hypothetical. One source2 summarizing third-party work cites roughly 0.05% to 0.30% a year for Vanguard, 0.2% to 0.5% for Fidelity and Schwab, and about 0.3% for Morningstar. These are illustrations, not guarantees, are based on differing assumtions and methodologies, and your result could be smaller or larger.
Practical limits
Liquidity needs. Money in a retirement account is generally not available without tax and possible penalties before age 59½. A strategy that puts the least liquid assets where you may need cash can cause problems.
Required minimum distributions. RMDs from tax-deferred accounts mean you must withdraw regardless of market conditions, which affects what you can keep invested there.
Rebalancing across accounts. To keep your overall allocation, you may need to trade in more than one account. Trades in tax-sheltered accounts do not create taxable gains, but trades in a taxable account can.
Contribution limits. The amount you can put in sheltered accounts is limited. For 2026, 401(k) deferrals are limited to $24,500 and IRA contributions to $7,500, which caps how much sheltered space you have.
Withdrawal order. Which account you draw from in retirement can affect Social Security taxation, IRMAA, and your bracket. Qualified Roth withdrawals generally do not count toward income for those purposes.
Behavior. A plan that is too complicated to follow may not be worth the modest benefit. Consistency and keeping costs low are usually more important than optimizing location.
Where location does not help much
- Small accounts. If most of your savings are in one type of account, there is little to optimize.
- Mostly tax-efficient holdings. An investor who holds mainly broad, low-turnover stock index funds may see little difference between accounts.
- Tax-managed funds. These are designed to limit taxable distributions, so placing them in a tax-deferred account may waste some of that benefit.
- Low brackets. If your tax rate is low or you are in the 0% long-term gains bracket, the gap between ordinary and capital gains rates matters less.
- A need for equities in the tax-deferred account. If your allocation requires holding stocks in tax-deferred space, the choice among stock funds for the taxable account has little net effect.
- Possible changes in law. Roth reasoning assumes current law continues. Future changes could alter the conclusion.
Asset location also does not justify skipping a retirement contribution. Tax-advantaged investing will generally beat taxable investing.
A note for business owners
If you have pass-through business income, a pass-through entity tax (PTET) election can change your taxable income and bracket, which affects the gap between ordinary and capital gains rates for your own location decisions. The impact will vary depending on your state's tax rules.
Questions to ask
- What is my overall allocation, and is it right for me?
- How much do I hold in taxable, tax-deferred, Roth, and HSA accounts?
- Which holdings generate the most taxable income each year?
- Are there holdings in a taxable account that could be placed more efficiently, and what would it cost in taxes to move them?
- Would moving assets trigger gains, and are those gains worth paying?
- Do I have enough liquidity outside retirement accounts?
- How will my withdrawal plan affect my taxes in retirement?
The bottom line
Asset location is a second-order decision. It may improve after tax outcomes, mostly for investors with meaningful balances in more than one type of account and holdings that are taxed very differently. It works only after allocation is settled, and it should be weighed against liquidity, simplicity, and the cost of moving assets. A tax professional and your adviser can look at it with your actual accounts.
Sources (as of November 2026)
- Q3 Advisors, Asset Location Strategy: Tax-Smart Account Placement (2026)
- Advisor Perspectives, Advanced Strategies for Investment Taxation
- Experian, Long-Term Capital Gains Rates for 2026
- IRS, 401(k) limit increases to $24,500 for 2026, IRA limit increases to $7,500