 Risk Capacity
 Wealth Management
 Outsourced CIO
 Retirement Plans
 Institutional
 Financial
 Open an Account

 IFA App


 Articles
 Charts
 Investor Education ▾

 Fund

 Store


 Taxes
 Back-testing Disclosures

 Glossary
 Form CRS
An investor looking at 98 years of market returns might reasonably ask: Isn't that enough data to know what to expect?
Statistics gives us a more useful answer. It is enough data to estimate certain characteristics of markets far more reliably than we could with a short track record. It is not enough data to know what markets will do next month, next year, or even over the next decade.
That distinction is the purpose of inferential statistics.
Descriptive statistics tell us what happened. Inferential statistics help us use what happened to estimate something we cannot directly observe: the underlying risk, expected return and uncertainty associated with future investment outcomes.
For investors, that distinction is enormously important.
Describing History vs. Learning From History
Suppose we calculate the average return, standard deviation, highest return and lowest return for an index. Those are descriptive statistics. They summarize the historical data we already have.
Inferential statistics ask a different question:
What can this historical sample reasonably tell us about the return-generating process we may experience in the future?
That is a much harder question.
IFA's historical Index data begin in January 1928 and incorporate index data from sources including Dimensional Fund Advisors, Fama/French research indexes and other public market index providers. A 98-year period represents approximately 1,176 monthly observations, far more information than the three-, five- or ten-year track records investors frequently use to evaluate investments.
But those 1,176 observations do not represent 1,176 observations of the future. They represent 1,176 observations of the past.
Inferential statistics provides a mathematical framework for determining how much confidence we should place in the estimates we derive from them.
The Most Important Distinction: Population vs. Sample
There is an interesting statistical paradox in long-term investment data. If our question is, "What was the average monthly return from 1928 through 2025?" we have the entire population of monthly returns for that period. There is nothing to infer. We can simply calculate the answer. But investors are rarely interested only in describing the past.
The more important question is:
What does this history tell us about the return's investors might experience in the future?
Now those same 98 years become a sample from a much larger—and unknowable—population of possible market outcomes. The future has not occurred yet.
That means expected return, future volatility and future risk premiums are not quantities we can observe directly. They must be estimated. This is where inferential statistics begins.
More Data Reduces Estimation Error
One of the most important ideas in statistics is surprisingly simple:
The larger the sample, the more precisely we can estimate its underlying mean.
The uncertainty surrounding an estimated average is measured by its standard error. For a simple sample mean:
Standard Error = Standard Deviation ÷ √n
where n is the number of observations.
Notice something important about that formula.
The benefit from additional data increases with the square root of the number of observations—not directly with the number of observations.
Consider 20 years versus 98 years of monthly returns. Twenty years provides 240 monthly observations. Ninety-eight years provides approximately 1,176 observations.
That is almost five times as much data. Yet, assuming similar volatility and sufficiently independent observations, the standard error falls by about 55%, rather than 80%.
The 98-year sample therefore gives us a substantially more precise estimate—but not a perfectly precise estimate.
There is always uncertainty.
Standard Deviation and Standard Error Are Not the Same Thing
Investors sometimes confuse these two statistics. Standard deviation measures the dispersion of the returns themselves. If monthly returns swing widely above and below their average, standard deviation will be high. It is a measure of the variability investors actually experience.
Standard error, in contrast, measures the uncertainty surrounding our estimate of the average return. As the number of observations increases, standard error generally gets smaller. Standard deviation does not necessarily get smaller. This creates an important result.
We can become increasingly confident about our estimate of the long-term average return while remaining highly uncertain about the return we will receive in any particular month or year.
The market does not become less volatile simply because we have studied it longer. We just become better informed about its historical characteristics.
Confidence Intervals: Replacing a Point Estimate With a Range
Suppose, purely for illustration, that we had 1,176 monthly observations for a hypothetical index portfolio with:
Average monthly return = 0.75%
Monthly standard deviation = 4.00%
The standard error of the estimated monthly mean would be approximately:
4.00% ÷ √1,176 = 0.12%
Using a conventional 95% confidence interval, we might estimate the underlying mean as approximately:
0.75% ± 1.96 × 0.12%
or roughly:
0.52% to 0.98% per month
This example is hypothetical and is not the performance of an IFA Index Portfolio.
The important point is the concept. Rather than pretending that 0.75% is the precisely known expected return, inferential statistics forces us to acknowledge a range of statistical uncertainty around our estimate.
A confidence interval is therefore much more informative than a single historical average. Under the standard statistical interpretation, a 95% confidence procedure is one that would capture the true underlying mean in approximately 95% of repeated samples generated under the assumptions of the model.
A Confidence Interval Is Not a Prediction Interval
This distinction is especially important for investors. A 95% confidence interval around an estimated average return does not mean 95% of future monthly returns should fall within that narrow range. Far from it.
In our hypothetical example, individual monthly returns still have a standard deviation of 4%. The uncertainty surrounding the mean may be relatively small because we have 1,176 observations. But the uncertainty surrounding the next month's return remains enormous by comparison.
This helps explain something investors experience constantly:
We can have reasonable confidence that equities offer a positive long-term expected return while having very little ability to predict whether stocks will be up or down next month. There is no contradiction. They are two different statistical questions.
The T-Statistic: How Strong Is the Signal Relative to the Noise?
Inferential statistics becomes particularly important when investors attempt to determine whether an observed return difference represents something meaningful—or simply randomness.
Suppose an active manager claims to have generated positive alpha, meaning returns above an appropriate risk-equivalent benchmark. A positive alpha alone tells us very little. We also need to know how consistently that excess return occurred.
The t-statistic combines these ideas:
t-statistic = Average Excess Return ÷ Standard Error of Excess Return
A large average excess return with very high variability may produce a low t-statistic. A smaller but highly consistent excess return may produce a higher t-statistic.
In conventional statistical applications, a t-statistic near 2 in absolute value is often used as a rough threshold for statistical significance at approximately the 5% level, subject to the assumptions of the test. This is why short fund-manager track records are so problematic.
A manager may outperform for five or ten years simply because of randomness. When excess returns are volatile, decades—or even far longer—may be required before the statistical evidence becomes strong enough to distinguish an apparent alpha from luck.
IFA's T-Stat Calculator demonstrates this relationship directly by showing how average excess return, variability and sample length interact.
Inferential Statistics Has a Different Role for Index Portfolios
The statistical question surrounding a broadly diversified Index Portfolio is different from the question surrounding an active manager. With an active manager, we might ask: "Is the manager's alpha statistically distinguishable from zero?"
With a diversified index-based portfolio, we are more interested in questions such as:
- What has been the historical relationship between risk and return?
- How widely have monthly returns varied?
- How much uncertainty surrounds our estimate of the long-term average?
- How frequently have positive and negative returns occurred?
- How have different levels of portfolio risk behaved across many different market environments?
- How wide has the range of investor experiences been over different holding periods?
These are exactly the types of questions for which a long historical sample becomes valuable. The objective is not to find a pattern that enables us to predict the next market move. It is to develop a better statistical characterization of uncertainty.
Why 98 Years Matters
Imagine trying to estimate the expected return of equities using only the previous three years.
The result could be dominated by a bull market, a bear market, inflation, recession, falling interest rates, rising interest rates, war, technological innovation or some other unusual period.
Extend the sample to 20 years and the estimate may become more statistically precise. Extend it toward a century and we incorporate vastly more economic and market environments.
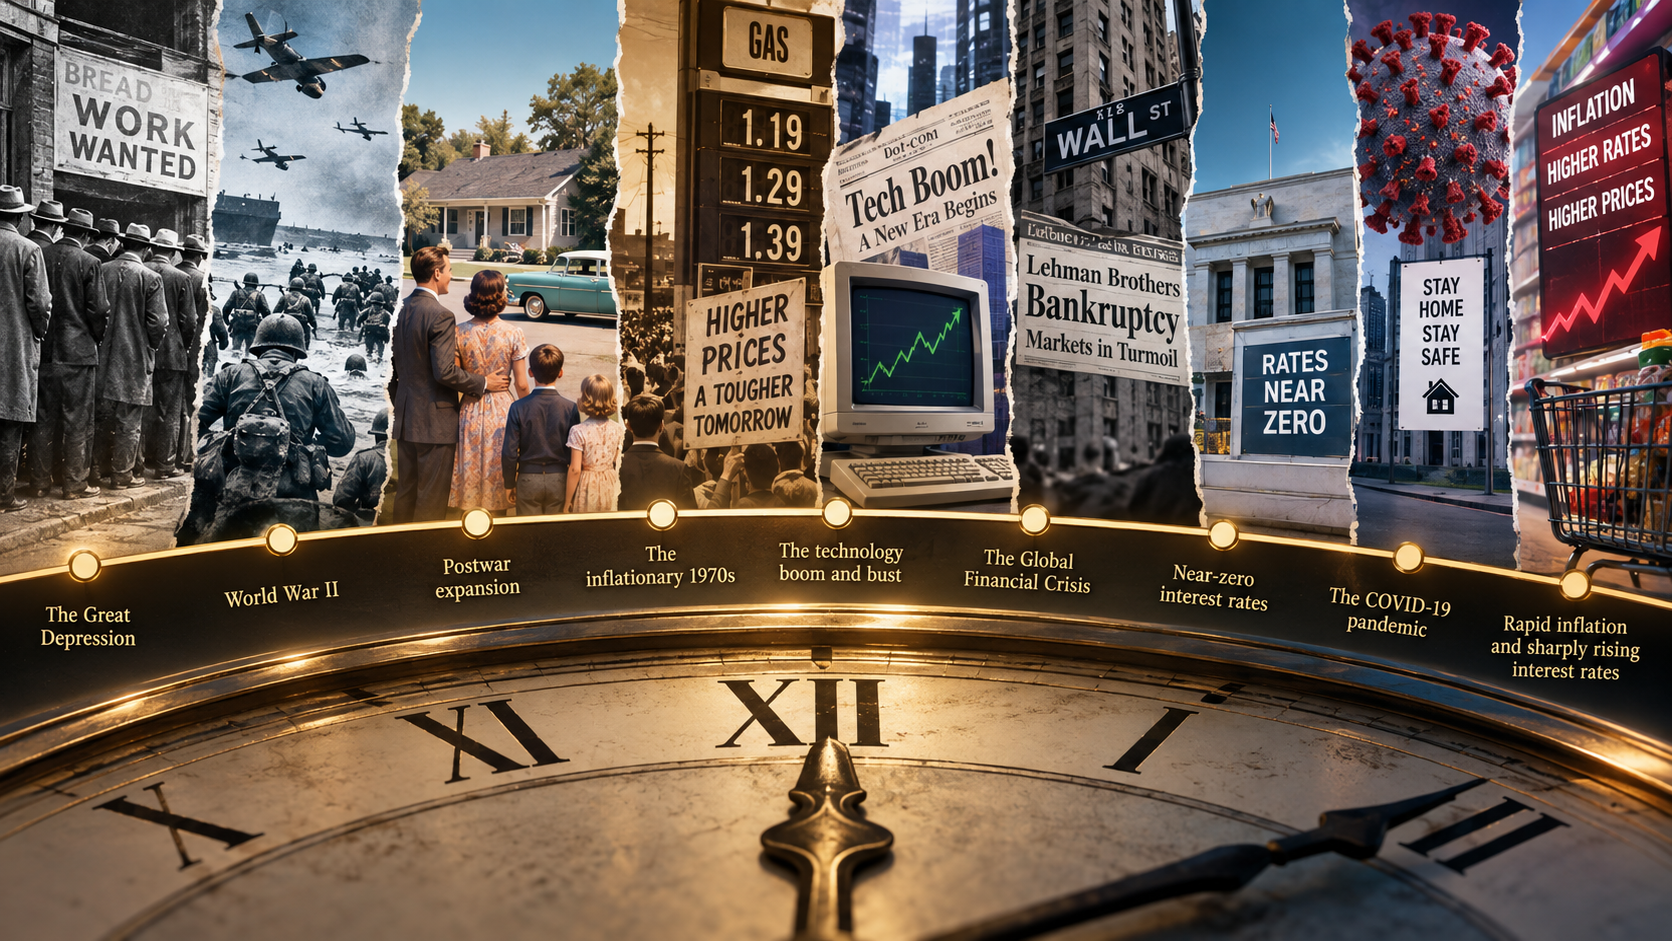
The Great Depression.
World War II.
Postwar expansion.
The inflationary 1970s.
The technology boom and bust.
The Global Financial Crisis.
Near-zero interest rates.
The COVID-19 pandemic.
Rapid inflation and sharply rising interest rates.
Each period adds information. No individual episode tells us what comes next. Collectively, however, they provide a much richer sample from which to estimate the risk and return characteristics of capital markets. That is the statistical value of long-term data.
But 1,176 Monthly Returns Are Not 1,176 Perfect Coin Flips
There is an important qualification. Many introductory statistical formulas begin with assumptions that observations are independent and generated by a stable underlying distribution. Financial markets are more complicated.
Market volatility can cluster. Calm periods can be followed by other calm periods, while highly volatile periods frequently occur close together. Risk premiums can vary through time. Interest rates, regulation, technology, market structure and the composition of the global economy change.
Market return distributions can also have more extreme observations than a simple normal bell curve would suggest. Therefore, simply having 1,176 observations does not mean every statistical assumption is perfectly satisfied.
Sophisticated statistical analysis can compensate for some of these issues through techniques such as robust standard errors, resampling and other methods.
But the broader lesson is more important for investors:
Beware of Data Mining
Inferential statistics also helps expose one of the great dangers in investment research: finding patterns after the fact.
Given enough securities, strategies, factors, time periods and possible trading rules, researchers can almost always discover something that appears statistically unusual. Some of those discoveries represent genuine relationships. Others are accidents. This is sometimes called data mining, data snooping or multiple testing.
A single result with an apparently impressive t-statistic becomes much less impressive if thousands of strategies were tested before it was discovered.
Investors should therefore ask not merely whether a result looks good historically, but whether it has a sensible economic explanation, whether the evidence survives different samples and whether it has been independently replicated.
Statistical significance should be evidence—not a treasure map for speculation.
What 98 Years of History Can Tell Us
Nearly a century of monthly data cannot tell us whether stocks will rise next month. It cannot tell us which country will outperform next year. It cannot tell us which asset class will rank first over the next five years. And it cannot eliminate the possibility that future markets will behave differently from historical markets.
What it can do is enormously valuable.
- It can reduce the estimation error associated with short samples.
- It can provide a much richer picture of market volatility.
- It can show investors the range of outcomes markets have historically produced.
- It can improve estimates of long-term risk and return relationships.
- And, perhaps most importantly, it can teach investors how much uncertainty remains even after examining an extraordinary amount of data.
Statistics Should Produce Humility, Not Certainty
Investors often turn to statistics hoping that enough mathematics will remove uncertainty. Good statistics teaches the opposite lesson.
The purpose of inferential statistics is not to make the uncertain appear certain.
It is to measure the uncertainty.
That is why 98 years of IFA Index and Index Portfolio history is useful. We do not study nearly a century of market returns because we believe history will repeat itself month by month. We study it because a large body of evidence gives us a better foundation for estimating risk and expected return than a small body of evidence.
The future remains unknown. But investors do not need to know the future to invest intelligently.
They need reasonable expectations, broad diversification, an appropriate exposure to risk, low costs, discipline and enough statistical understanding to recognize the difference between evidence and prediction.
That is one of the most valuable lessons inferential statistics can teach an investor.
Important Disclosure
IFA Indexes represent hypothetical historical index data and the IFA Index Portfolio results discussed on IFA.com are hypothetical back-tested/model performance; they do not represent the actual performance of any client account. IFA's current Index time series covers the period beginning January 1, 1928 through December 31, 2025, and is constructed from index data from various sources. Performance of IFA Index Portfolios is shown net of IFA's highest advisory fee and underlying fund expenses, while individual IFA Indexes do not reflect an IFA advisory fee. Trading costs and taxes are not reflected and would reduce applicable returns. Back-tested performance has inherent limitations, and past performance does not guarantee future results. Readers should review IFA's complete current disclosures before relying on any performance presentation. Artificial intelligence tools were used to assist with editing and content organization. The final content was reviewed and approved by IFA personnel.







 Home
 888-643-3133
 Contact Us
 Newsletter Subscribe
 eMoney
 IFA Apps
 Index Funds Book on Kindle
 Index Funds Audiobook
 Careers
 Facebook
 X
 LinkedIn
 Instagram
 Youtube
 Terms
 Index Descriptions